


Your AI vendor might not survive the next 90 days
Brenton O’Callaghan at Avantra has a warning for enterprise leaders currently under pressure to lock in their AI vendors: the market is moving too fast for procurement to keep up, and betting on the wrong platform now could cost you


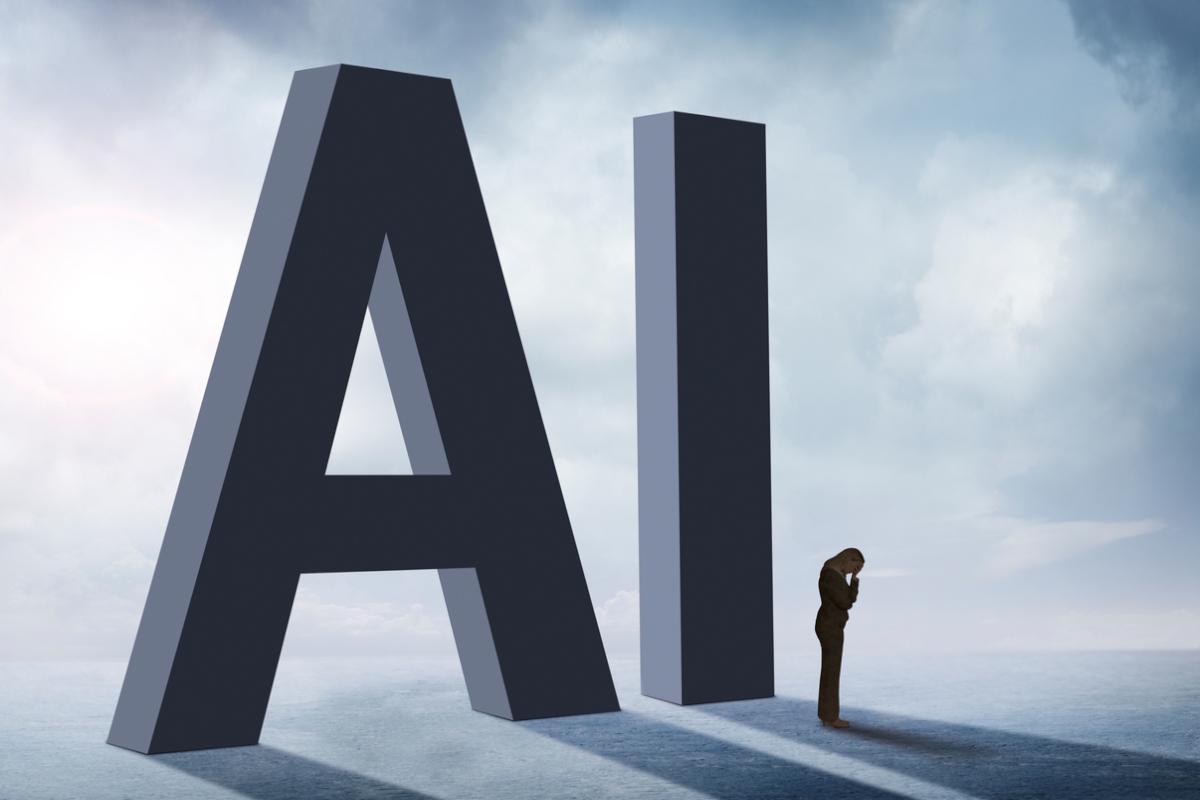
Towards the end of 2022, momentum started to build around enterprise AI adoption. Convinced by the promise of the technology, businesses have spent the subsequent years investing in AI across a wide range of marketing tools, sales tools, developer platforms, analytics, and automation platforms. Three years on, that experimentation has produced a strange paradox: adoption has never been higher, and confidence has never been lower.
A Domino Data Lab study released in July found that 57% of enterprises’ AI ROI still fails to outpace their investment, a figure that hasn’t moved since 2025, even as 93% of the same companies report improved production capability. Independent research from MIT’s NANDA initiative goes further, finding that 95% of organisations running AI pilots have seen no measurable profit-and-loss impact at all. The technology works well enough to deploy. Very few companies can yet show it pays for itself.
Today, however, the focus is beginning to shift. Now, enterprise leaders are putting their AI systems under review and asking, “Are the outcomes worth the price?” PwC’s 2026 Global CEO Survey found only 12% of chief executives can point to both revenue growth and cost reduction from their AI spend, while 56% say they’ve seen no significant financial benefit at all. That gap between deployment and proof is exactly where boards are now focusing their questions.
To some extent, this is a consequence of just how heavily some organisations have invested in the technology. Some businesses support AI portfolios worth up to five points of EBITDA (figures from BCG put the average spend this year at 1.7% of revenues). Given how much is being spent, the pressure to demonstrate returns is building.
Over the next 12-18 months, we can expect to see something of a reckoning. Gartner already predicts more than 40% of agentic AI projects will be cancelled by 2027 due to unclear ROI and weak governance. Vendors with products that deliver only marginal productivity gains can expect to lose out to competitors that offer better value for money. This phase of market consolidation will likely be significant, and it’s possible that many of the AI companies that attracted serious enterprise contracts over the last two years will struggle.
A vendor landscape that won’t sit still
AI platforms don’t improve at a predictable pace, and that unpredictability is what makes this moment risky. In the early days of the internet, AltaVista was one of the leading web search pioneers. It had an early-mover advantage and, in the early days at least, a strong user base. AltaVista lost out to Google, a new kid on the block with much better technology. Google won because it learned where the pioneers were going wrong and overtook them through rapid technological advancements.
Today, many current AI leaders risk being leapfrogged in the same way. Indeed, the environment today is much more perilous to first-wave pioneers than it was back in the mid-nineties. A standard enterprise procurement cycle (RFP, shortlist, pilot, legal sign-off) can run six to nine months. In AI terms, that’s long enough for two or three capability generations to come and go, and a leading platform in any given category today may slide into distant second in as little as 90 days.
This creates a strategic trap for enterprise IT users. Businesses that standardise too early risk being locked into a platform that’s soon out of date. If organisations delay key decisions too long they may fail to capture the productivity gains that competitors are already realising.
The best course of action is to track close enough to the market to understand its direction of travel without overcommitting. Practically speaking, this requires carrying out regular technology evaluations while keeping options open across two or three platforms. It’s also important to resist pressure from vendors to sign long-term contracts for platforms that are still in development or to undertake complex integrations. Vendors pressing hardest for long-term commitment are often the ones with the most to lose if you wait.
Knowing a settled category when you see one
The one major caveat to all this is that in a few niche areas a clear leader will have already emerged, the Googles to the AltaVistas of this world. In these cases, the gap between the leaders and the rest is so large it’s unlikely to be closed anytime soon. Here, businesses can invest with much greater confidence.
Developer tooling is the clearest example. Enterprises that have evaluated every serious option for AI-assisted coding, including the less widely discussed platforms, keep arriving at the same conclusion: one platform now outperforms the rest by a margin wide enough that there’s little real debate. For most dev teams, that dominance is strong enough to justify retiring licences for the alternatives altogether and consolidating spend onto a single platform.
That kind of clarity is useful, and organisations should act on it where they find it. The mistake is assuming that because one category has settled, the others have too. KPMG’s June 2026 pulse of over 2,000 global leaders found only 7% report an established AI ROI framework, a sign that in most categories, including AI-assisted design, marketing content generation, and enterprise search, the picture remains genuinely unsettled and standardising now carries real risk.
Reading the signs of a coming shakeout
The tools that survive the coming reckoning will share three traits: they’re embedded deep in a workflow, tied to outcomes a finance team can actually verify, and expensive enough to switch away from that users don’t jump ship the moment a rival ships an update.
Tools that fail those tests will face a sharp correction. Acquirers will buy some for their user base or technical team. Others will simply lose enterprise renewals at a rate that’s not sustainable.
Organisations best placed to navigate this period of market turbulence will have maintained honest internal records of what value their AI investments actually deliver. Success should show up as measurable gains in output, quality, or cost at a team or process level, not anecdotal evidence from enthusiastic early adopters. That discipline is harder to maintain during the experimentation phase, and it separates the organisations that will make smart consolidation decisions from those that will cut platforms indiscriminately when the pressure arrives.
Three moves for the next 18 months
As organisations review their AI investment strategy, there are three fundamental steps to take:
- Resist multi-year platform agreements in categories where the technology is still visibly moving.
- Document what your AI tools are actually producing in terms that will survive a CFO’s scrutiny.
- Move decisively in categories where consolidation has already happened.
When your board asks what the company is spending on AI, make sure you walk in with two numbers: what you are spending, and what you are getting. With only 7% of enterprises able to point to an established ROI framework, that second number is still rare enough to be a genuine competitive advantage. The organisations that cannot produce it are the ones that will be cutting indiscriminately in 18 months. The rest will be compounding the advantage they have already built.
Brenton O’Callaghan is Chief Product Officer at Avantra
Main image courtesy of iStockPhoto.com and DNY59
Your Next Read
Related Content
2025 Privacy Benchmarks: AI readiness and winning movesSPONSORED ARTICLE
2026 Revenue Revolution: Addressing Six Critical B2B ChallengesSPONSORED ARTICLE
4 key steps to prepare for post-quantum cryptographySPONSORED ARTICLE
Supply Chain Talk
view all
Why unified, AI-powered supply chains are pulling ahead - and what the rest risk losing
Connecting the supply chain - Why the yard matters more than ever
Winston House, 3rd Floor,
Units 306-309, 2-4 Dollis park,
London, N3 1HF
020 8349 4363
© 2026, Lyonsdown Limited. teiss® is a registered trademark of Lyonsdown Ltd. VAT registration number: 830519543